

Updated: October 13th 2026
What is a DDA deposit?
A DDA deposit is money credited to a demand deposit account: a bank account you can draw on at any time without giving the bank notice, such as a checking account.
If you see “DDA deposit” on your statement, money has landed in your everyday account. It’s usually a paycheck, but tax refunds, government benefits, and transfers show up the same way.
Note: “DDA” can also stand for direct debit authorization, meaning permission for a company to pull money from your account. On most statements, though, DDA refers to the account type: a demand deposit account.
What DDA codes mean on a statement
Banks abbreviate transaction types, and the abbreviations vary by institution. These are the most common ones tied to a demand deposit account:
Statements always describe direction from the account holder’s point of view. A DDA credit means money in, and a DDA debit means money out. The same payment looks different on each side: a deposit that shows as a credit on your statement is a debit on the sender’s.
Where do DDA deposits come from?
A DDA deposit can come from any payer that sends money electronically to your account. The most common sources are:
- Your paycheck, sent by your employer or payroll provider
- Tax refunds from the IRS or your state
- Government benefits, such as Social Security or unemployment
- Gig and contractor payouts from apps and platforms
- Transfers from another account of yours or from someone else
The amount and date on your statement usually help you match a deposit to its sender.
Is a DDA deposit the same as a direct deposit?
Most direct deposits travel over the ACH network in the US (or EFT in Canada). In the US, standard ACH payments typically arrive within one to two business days, and same-day ACH can deliver funds within the same business day when the payer and their bank use it. Employers often send payroll files early so funds are available on payday.
Why is my DDA deposit pending?
A pending deposit is usually still moving through ACH processing or waiting for your bank to post it. Timing depends on when the payer sent it and on each bank’s processing schedule. If a deposit takes longer than expected, check with the payer that they sent it to the right account.
- Checking accounts are transactional accounts for paying bills and handling daily spending. Because the bank cannot count on the balance staying put, they usually pay little or no interest. Minimum balance rules vary widely by institution, with some waiving monthly fees above a threshold and others charging none at all.
- Savings accounts are more likely to earn interest, at higher rates than checking, and more likely to carry a minimum balance. Some institutions cap the number or method of withdrawals per month or charge a fee beyond that limit, which is why some definitions exclude savings accounts from the DDA category.
- Money market accounts sit alongside savings accounts, usually with a higher rate, a higher minimum balance, and often a monthly withdrawal cap.
DDA deposits to a payroll or prepaid card
You don’t need a checking account to receive a DDA deposit. Many payroll and prepaid cards have their own routing and account number behind them, so employers and other payers can send money straight to the card. In many programs, this happens behind the scenes: your employer or the platform paying you sets it up, and you never need to see the number.
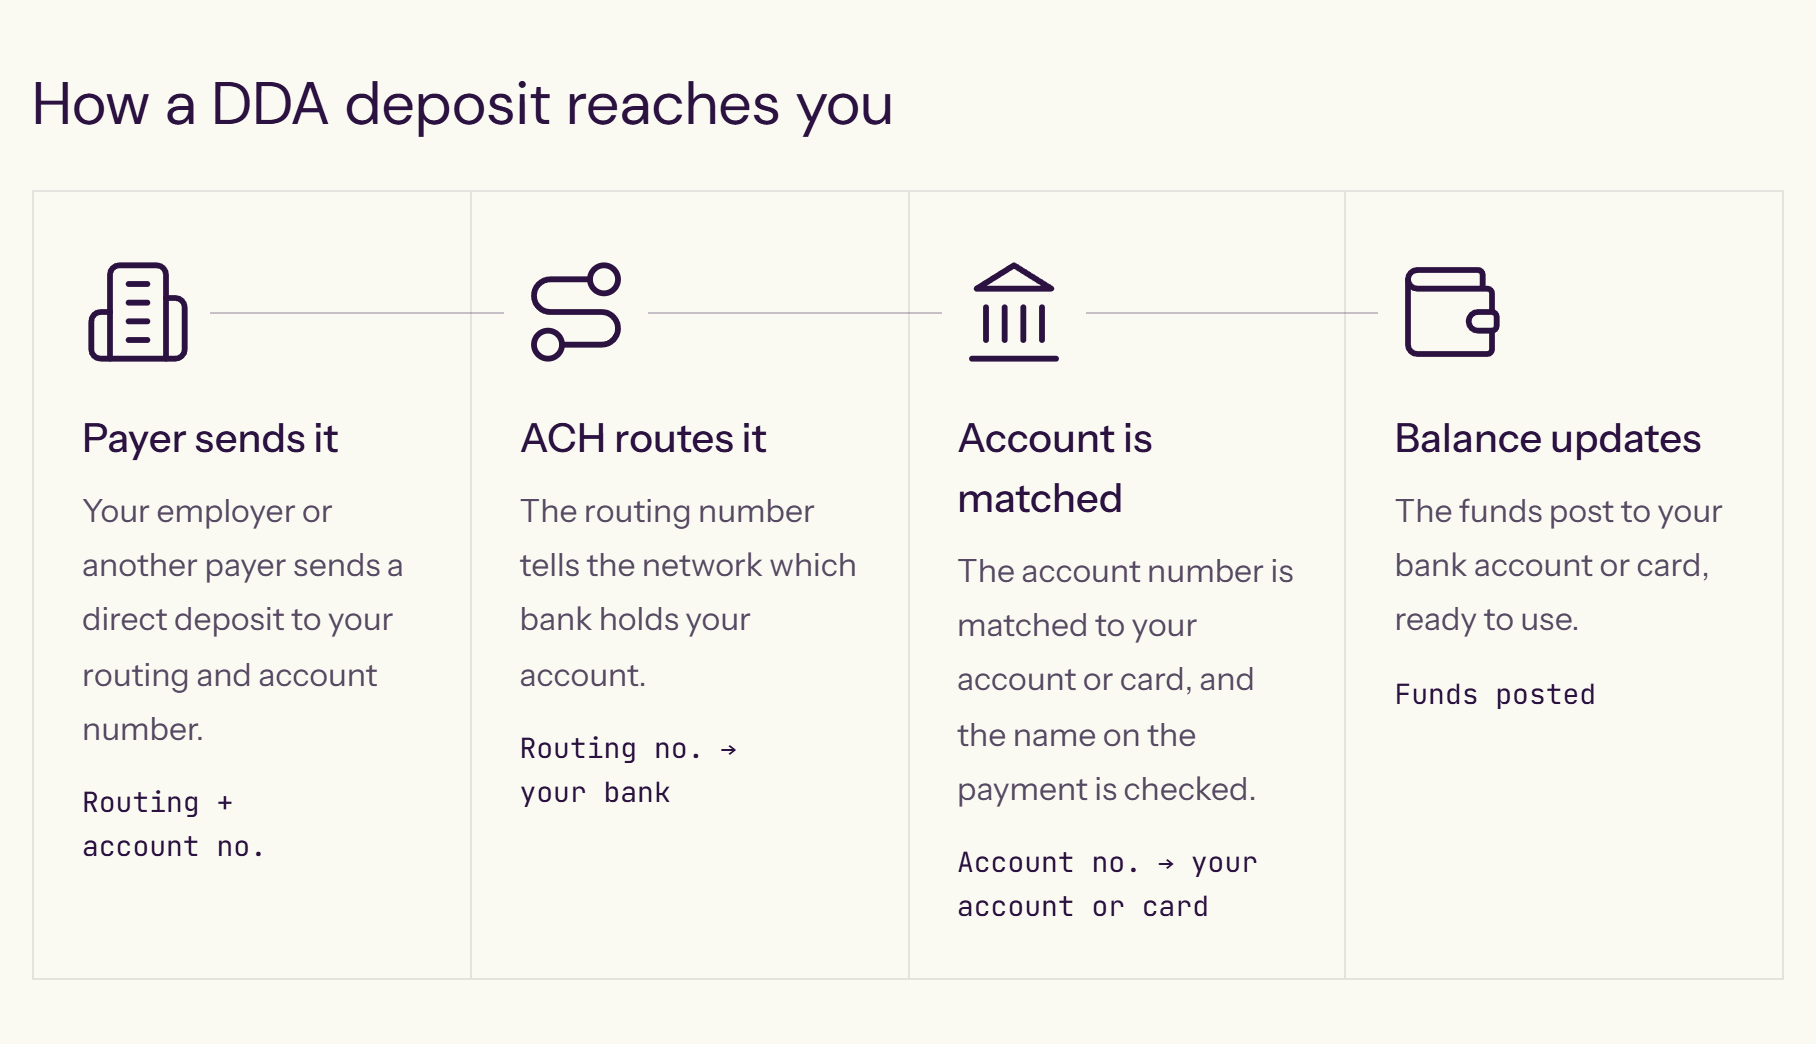
How the money reaches your card
- The payer sends the payment. Your employer or another payer sends a direct deposit using the card account’s routing and account number, the same way it would pay a checking account.
- ACH routes it to the issuing bank. The routing number tells the ACH network which bank issued your card account.
- The bank matches the account number. The bank recognizes the account number and identifies the card it belongs to.
- Your card balance updates. The funds post to your card, ready to spend anywhere the card is accepted.
Your account number is not your card number
The routing and account number used for direct deposit differ from the 16-digit number on the front of your card. Each card account gets its own unique account number, so payments go to the right person. In many programs, your employer or the paying platform manages this number for you, so you may never need to see it. In others, you’ll find it in your card’s app or online account.
If your card is lost or replaced, your deposit details usually stay the same, because the account number belongs to your account rather than the physical card. If you’re unsure, check with your card provider before your next payment.
What counts as a demand deposit account?
A demand deposit account has two defining features: no lock-up period and no notice requirement. You don’t need to tell the bank in advance that you want your money, and you don’t have to wait a set term to access it.
Types of DDAs
Checking accounts handle bill payments and daily spending. Because the balance moves constantly, they usually pay little or no interest. Minimum balance rules vary widely by institution.
Savings accounts are more likely to earn interest and to carry a minimum balance. Some institutions limit withdrawals each month or charge a fee beyond that limit, which is why some definitions leave savings accounts out of the DDA category.
Money market accounts usually offer a higher rate than savings accounts in exchange for a higher minimum balance, and often a monthly withdrawal cap.
How DDAs differ from term deposits and investment accounts
A term deposit, such as a certificate of deposit (CD), holds your money for an agreed period. Withdrawing early triggers a penalty, but the yield is higher because the bank knows how long it will hold the funds.
Investment accounts hold assets rather than cash. You can sell those assets, but it takes several business days before the cash becomes available.
For employers: paying wages into payroll cards
Why employers make DDA deposits into payroll cards
Paying employees requires an account to pay into. For most of the workforce, that means a checking account. But not everyone has one.
In the US, about 5.6 million households are unbanked, and about 19 million more are underbanked, meaning they hold an account but rely mainly on non-bank products.
A payroll card is a reloadable prepaid card issued to an employee, onto which wages are loaded. The employee uses it like any debit card: for purchases, online payments, or ATM withdrawals.
Because the card account has its own routing and account number, you can pay it through the same direct deposit file as a bank account. No separate process, no paper checks.
Traditional checking vs payroll card vs gift card
Control how money moves
Every card account comes with its own routing and account number for receiving direct deposits. What happens after that depends on how the program is set up.
Most of our clients choose to keep funds tightly controlled, so the account only accepts incoming deposits. Pre-authorized debits can be switched off, and debits can never take the card below zero. That protects the cardholder’s pay and closes the paths fraudsters typically rely on. Programs that need more flexibility can allow pre-authorized debits, which only ever draw on the available balance.
Beyond payroll
The same mechanism works for any organization that pays people by direct deposit: tax preparers delivering refunds, benefit programs, gig platforms, and insurers paying claims. Many legacy payroll and government systems can only pay to a routing and account number. A card account with its own account details lets those systems pay straight onto a card, with no changes on the payer’s side.
Some payment types carry extra requirements. Federal payments delivered to prepaid cards, for example, must meet specific US Treasury conditions.
Confirm the rules for your program with a qualified advisor before launch.
What regulations apply to payroll cards?
Payroll cards sit under several overlapping sets of rules, and the details vary by country, by state or province, and over time as regulations change.
Treat this section as a general overview to help you ask the right questions, not as legal advice or a complete list. Before launching or joining a payroll card program, confirm the current requirements for your specific jurisdiction with a qualified advisor.
With that in mind, here are the main areas that tend to apply.
In the United States, payroll card accounts are generally subject to Regulation E (12 CFR 1005.18), which sets out disclosure, balance-access, and error-resolution requirements intended to give people safe access to their earned wages.
The Electronic Fund Transfer Act is generally understood to prevent employers from requiring employees to receive wages at one particular institution, which means a payroll card typically cannot be the only option. Employers usually need to offer an alternative as well, such as direct deposit to an account the employee chooses, or a check.
Most states add their own rules. Common requirements include:
- Voluntary written consent, obtained without coercion and revocable at any time.
- Written disclosure of fees, and of the fee-free ways to access wages, before consent is given.
- At least one free withdrawal of the full net wage per pay period, with some states requiring more.
- Limits on making payroll card use a condition of hire or continued employment.
Fees deserve attention too. Under the Fair Labor Standards Act, regulators have generally taken the view that card fees that push an employee’s effective pay below minimum wage can raise a wage-and-hour concern, even when the employee agreed to the card.
The obligations are manageable, but they’re real, and getting advice up front pays off.
Paying employees in Canada?
The same approach works over Canada’s EFT system. Instead of a routing number, Canadian accounts use a three-part number: institution, transit, and account. Payroll systems and government payers such as the CRA can pay to those details, and the funds land on the card. Wage payment rules in Canada sit within provincial employment standards legislation, so check the rules for each province you operate in.
When a payroll card isn’t the right answer
Payroll cards solve a specific problem. They aren’t a general upgrade over direct deposit to a bank account:
- If you can’t support the compliance obligations, don’t run the program. Consent tracking, fee disclosure, and fee-free wage access are ongoing responsibilities.
- If the payment is one-off, promotional, or event-based, a payroll card is the wrong tool. Those cases call for a different type of card.
Choosing a partner
Running a payroll program means owning the disclosure and access obligations above, plus the day-to-day reality: lost cards, funds that must arrive on time, and a ledger that reconciles at month’s end.
Berkeley Payments builds white-label card and payment programs for organizations in the United States and Canada, including payroll and payout programs with a dedicated account number behind every card.
Talk to our team about how a payroll card program would work for your organization.
Frequently asked questions
Why did I get a DDA deposit?
Someone sent an electronic payment into your account. Usually it’s a paycheck, but it can also be a tax refund, a government payment, or a transfer. The amount and date on your statement usually help you match it to the sender.
What is a DDA deposit on a bank statement?
It’s a credit to your demand deposit account: money that entered your everyday account, typically a checking account. “DDA” refers to the account type, and “deposit” means money coming in.
Is a DDA deposit the same as a direct deposit?
They overlap but aren’t identical. Direct deposit is the method of sending money electronically, and a DDA deposit describes the account it lands in. A direct deposit into your checking account is both.
Why is my DDA deposit pending?
The payment is usually still moving through ACH processing or waiting for your bank to post it. In the US, most direct deposits arrive within one to two business days of the payer sending them. If it takes longer, check with the payer that they sent it to the right account.
Is my DDA account number the same as my card number?
No. Your direct deposit account number is separate from the number printed on your card. Depending on your program, you may find it in your card’s app or online account, or your employer or paying platform may manage it for you.
Why was my DDA deposit returned?
A deposit can bounce back to the payer if the account it was sent to is closed, the account number doesn’t match, or the details are wrong. If a payment you expected was returned, contact the payer to confirm your current deposit details.
Can a tax refund go to a prepaid card?
Often, yes, if the card account has its own routing and account number and meets the requirements for that payment type. Some tax preparers set this up for you. If you’re entering the details yourself, get them from your card provider first.
How do direct deposits to cards work in Canada?
Canada uses EFT instead of ACH, and accounts are identified by an institution number, transit number, and account number. A card account with those details can receive payroll and government payments just like a bank account.
